
Market Summary October 2026
November 11, 2026
Markets After Midterms
In each of the nine previous cycles, the S&P 500 was higher 12 months after Election Day. The average total return over that period was 16.9%, with the best year coming after 1994, when the market advanced by over 30%.
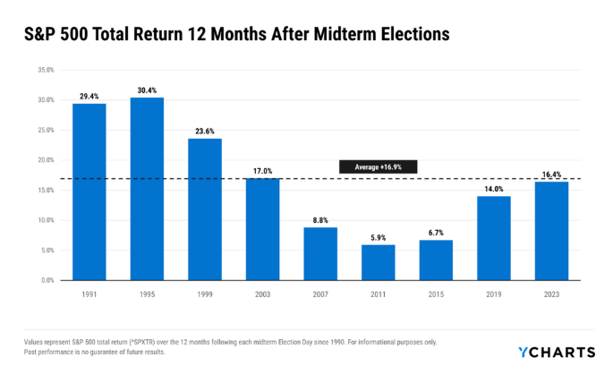
This streak isn’t just limited to the past 35 or so years, either. Since the index was established in the 1950’s, there has never been a negative return in the 12 months following a midterm election.
So, for clients, is it really that simple? 19/19 previous cycles, 100% of the time, the market was higher once November came back around. Unfortunately, nothing is ever that easy, and as advertised on almost every chart, “Past performance is no guarantee of future results.”
Equity Performance: Emerging Markets Fall 8%, Defensive Sectors Gain as Semiconductors Stumble
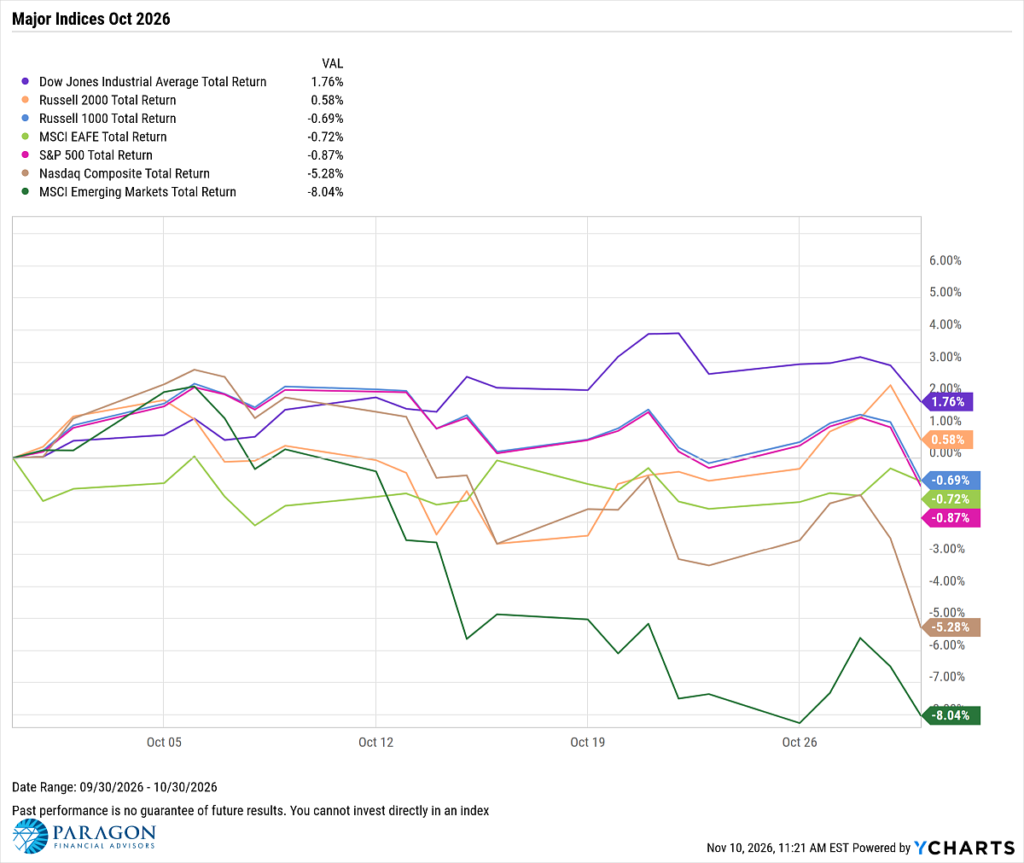
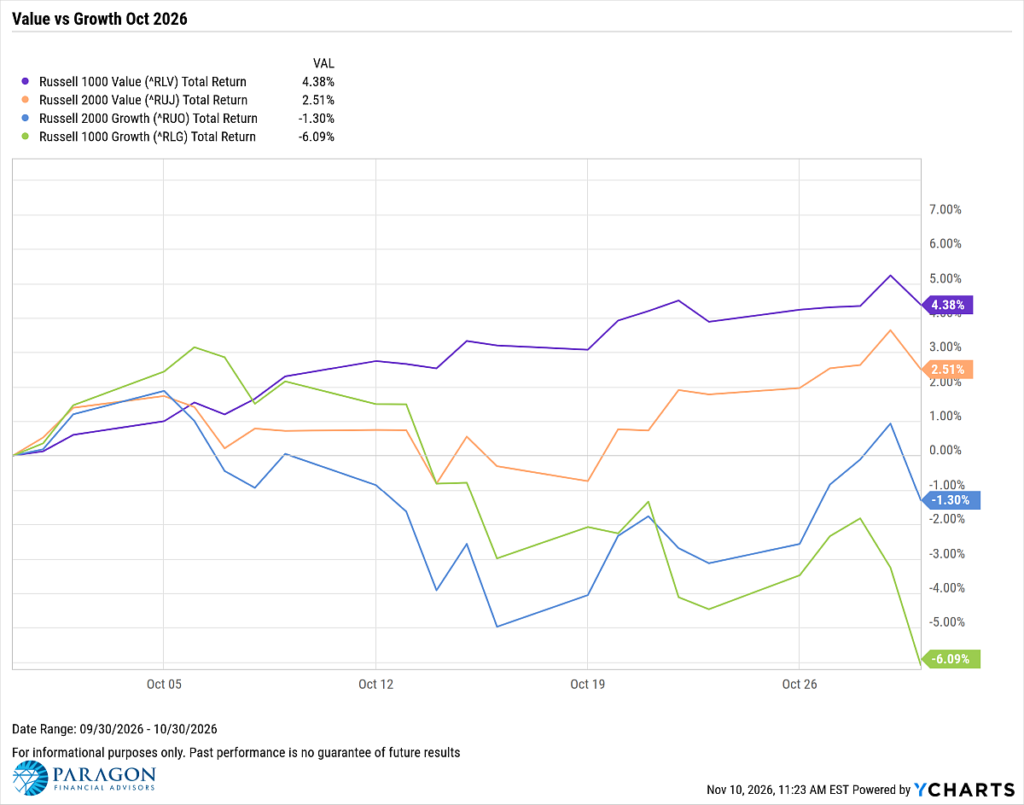
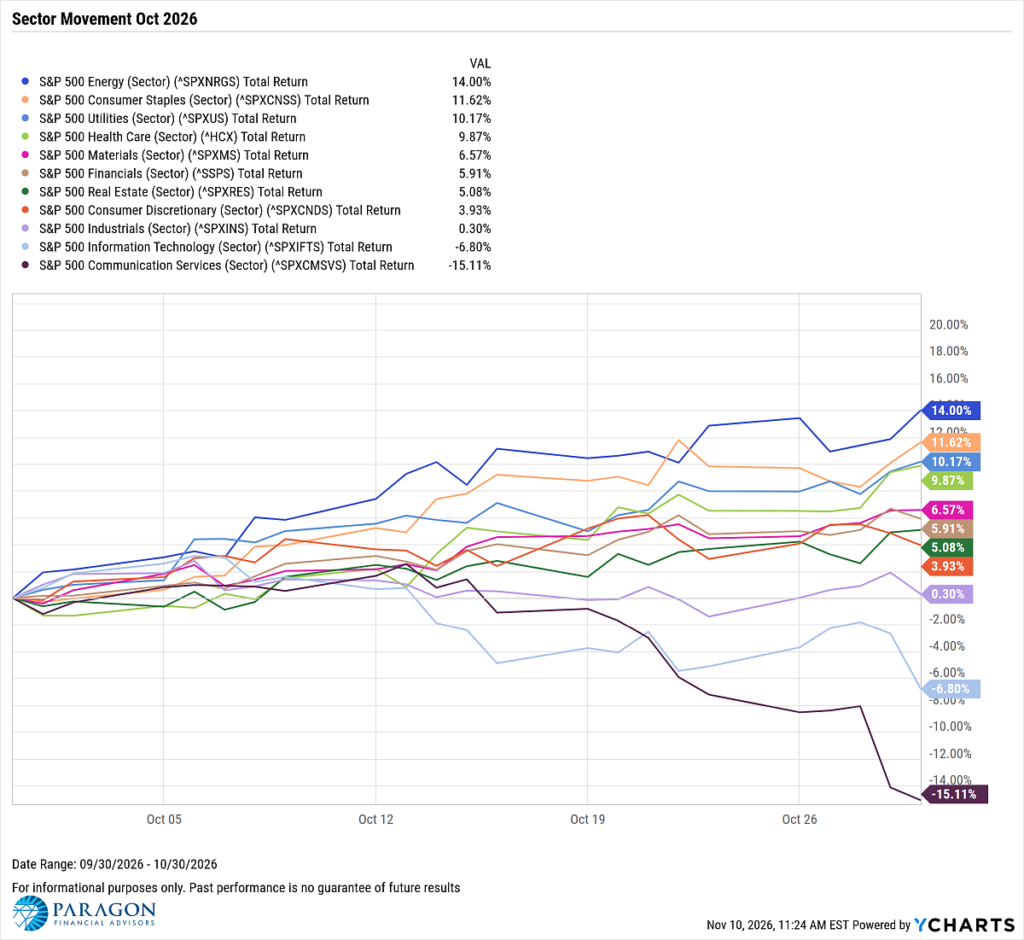
Markets were mixed in October, the result of polarizing returns across sectors and styles. The Dow Jones led all indices, up 1.76%, while Emerging Markets fell by more than 8%. Defensive sectors posted a strong month, though Energy led all returns up 14%, as Communication Services fell over 15%. Large-cap Value advanced by 4.4% and Large-cap Growth declined by 6.1%.
Economic Data Overview: Inflation Runs Hot as Jobs Reports Concern, Fed Holds Rates Steady
The economy added just 22,000 jobs this month, while the unemployment rate rose 0.1 percentage point to 4.2%. Inflation came in hot once again, increasing by 0.3 percentage points to 3.70%. The Fed held rates steady, with markets anticipating one additional rate hike at the final FOMC of the year, as the 30-year mortgage rate touched levels not seen since November 2023.
Employment
The unemployment rate increased by 0.1 percentage point to 4.2% in September, as the US economy added just 22,000 jobs, according to the most recent nonfarm payrolls report. This came in well below the consensus estimate of 84,000. The US Labor Force Participation Rate increased by 0.2 percentage points for a second consecutive month, to 61.80% in August.
Consumers and Inflation
The US inflation rate increased by 0.3 percentage points to 3.70% in September. Core inflation also increased, jumping 0.2% MoM to 2.60%. The CME FedWatch tool indicates a 75% chance of a 25-basis-point hike when the FOMC meets for the final time in 2026 on December 9th.
Production and Sales
The US ISM Manufacturing PMI increased by 1.1 points in October to 55.5, its first positive change since July. The Services PMI decreased by 0.5 points to 54.9 in September, still awaiting October’s reading. The YoY US Producer Price Index ticked up 0.7% in September to 6.30, its highest reading since December 2022, while US Retail and Food Services Sales grew by 0.77% MoM.
Housing
Existing Home Sales increased by 1.53% MoM in September, while the Median Sales Price of Existing Homes fell by 2.38%, down to $417,500. Mortgage rates continued to climb, with the 15-year sitting at 6.60% and the 30-year at 7.24%, both as of October 29th. The 30-year reached as high as 7.40% intra-month, its highest reading since November 2023. US New Single-Family Home Sales fell by 0.59% MoM in September.
Commodities
Gold and Silver prices both fell sharply in October, a second consecutive month of meaningful losses. SPDR Gold Shares (GLD) dropped by 6.58% to end the month at $355.78 per share, while the iShares Silver Trust (SLV) fell by 18.18% to settle at $44.60.
Oil prices increased once again in October as the conflict in the Middle East continues. One barrel of Brent crude now costs $125.78, up 8.52%, with WTI up 3.79% to $100.86 per barrel. The US Retail Gas Price fell 2.02% to $4.41 per gallon in October.
Cryptocurrencies
Major cryptocurrencies reversed course in October, following what was a strong September. The price of Bitcoin fell 7.7% to $77,233.17 per coin, while Ethereum dropped 16.24% to $2,242.50.
Fixed Income Performance: Insights into Bond ETFs and Treasury Yields
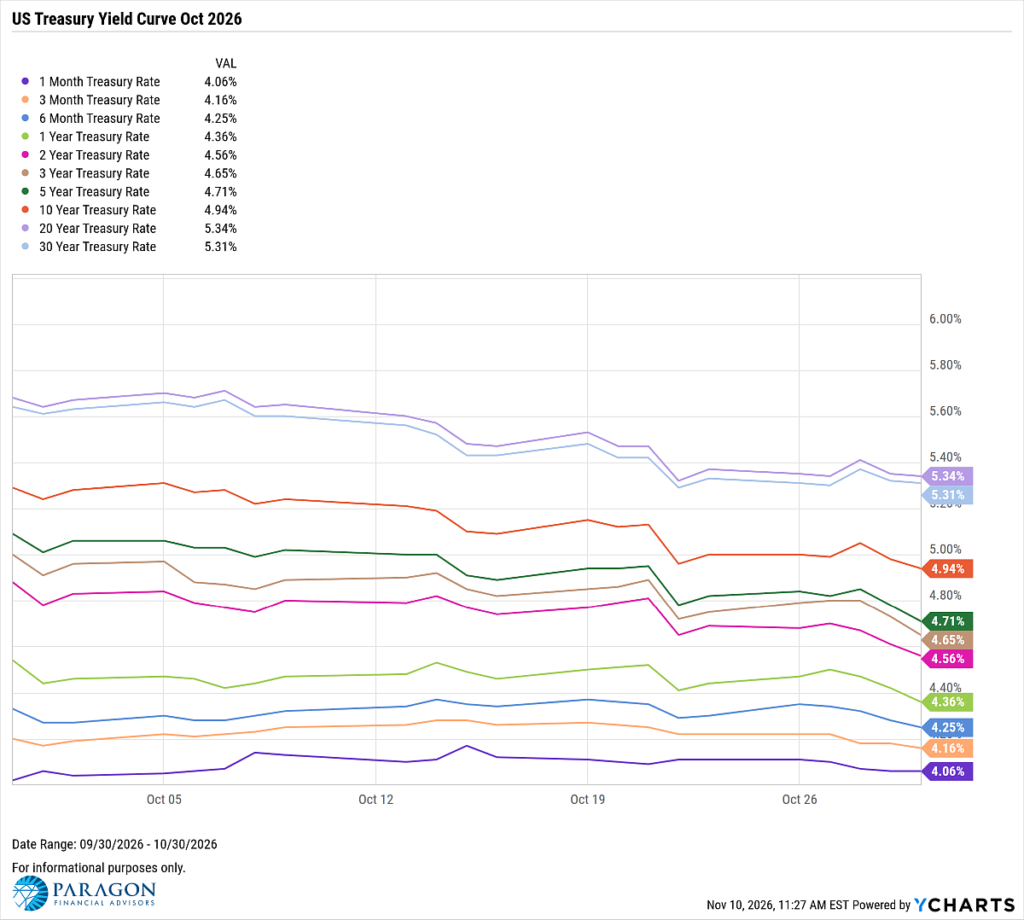
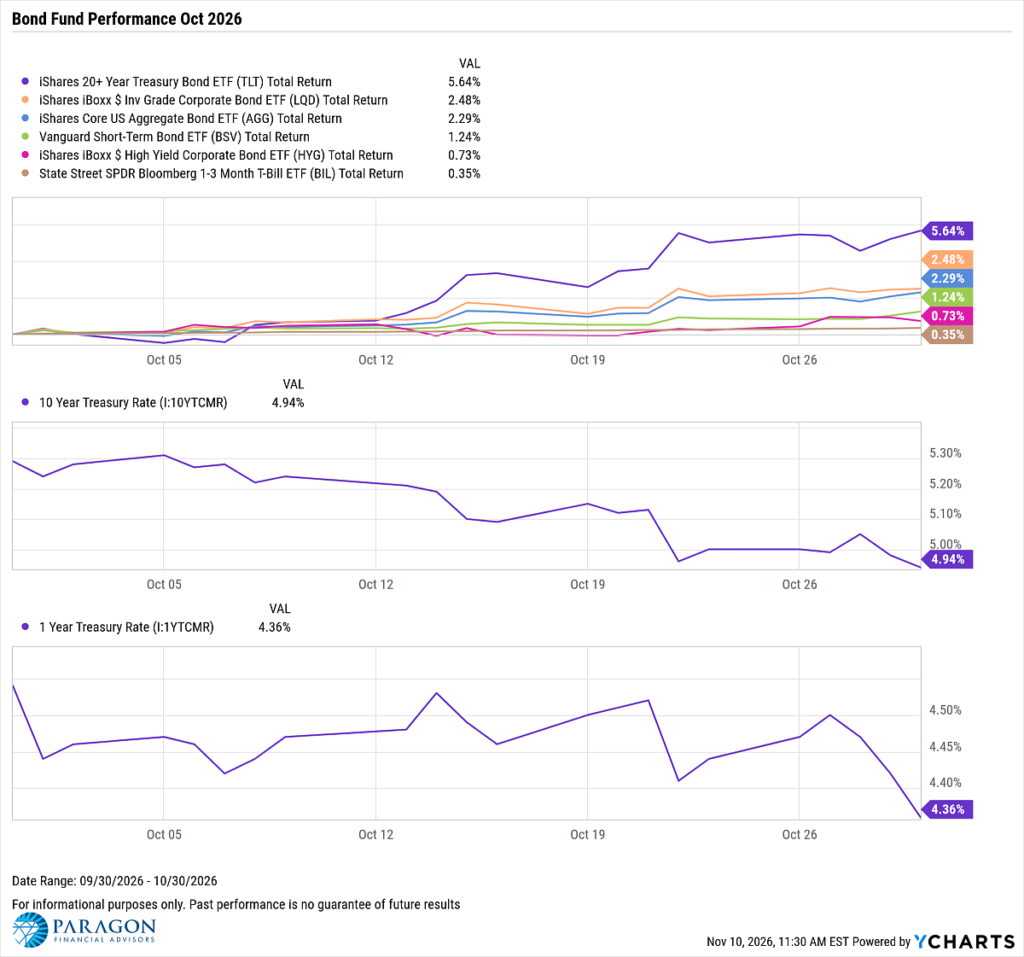
Treasury yields fell across the curve, aside from the 1-month. Most notably, the 10-year dipped below 5% in October, down 35 basis points. The 5-year saw the biggest decline, down 38 basis points after spiking 60 basis points in September. In fact, each duration, including the 2-year and longer, dropped by 30 basis points for the month.
Disclaimer
©2026 YCharts, Inc. All Rights Reserved. YCharts, Inc. (“YCharts”) is not registered with the U.S. Securities and Exchange Commission (or with the securities regulatory authority or body of any state or any other jurisdiction) as an investment adviser, broker-dealer or in any other capacity, and does not purport to provide investment advice or make investment recommendations. This report has been generated through application of the analytical tools and data provided through ycharts.com and is intended solely to assist you or your investment or other adviser(s) in conducting investment research. You should not construe this report as an offer to buy or sell, as a solicitation of an offer to buy or sell, or as a recommendation to buy, sell, hold or trade, any security or other financial instrument. For further information regarding your use of this report, please go to: ycharts.com/about/disclosure
RISK DISCLOSURE: Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values. Past performance does not guarantee future results.
This material is for information purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. For illustrative use only.
SECURITY REMINDER: E-mail transmission may not be secure. If you would like to be contacted by other means please alert Paragon Financial Advisors. By your use of email, Paragon Financial Advisors assumes you agree to our transmission of information by e-mail. Please do NOT send Social Security numbers or account numbers, confidential or privileged information via E-mail.
CONFIDENTIALITY NOTICE: All e-mail sent to or from this address will be received or otherwise recorded by Paragon Financial Advisors and is subject to archival, monitoring or review by, and/or disclosure to the Securities and Exchange Commission. This email and any files transmitted with it are confidential and are intended solely for the use of the individual or entity to which they are addressed. This communication represents the originator’s personal views and opinions, which do not necessarily reflect those of Paragon Advisors. If you are not the original recipient or the person responsible for delivering the email to the intended recipient, be advised that you have received this email in error, and that any use, dissemination, forwarding, printing, or copying of this email is strictly prohibited. If you received this email in error, please immediately notify info@paragon-adv.com
Category

© 2026 Paragon Advisors, LLC. All rights reserved. | Site Credit: Kasey S Consulting